

EdTech Isn’t One Industry. It’s Nine.
By: Ian McCullough
Ian McCullough is an EdTech marketing executive who lives in the San Francisco Bay Area. You can learn more about him on LinkedIn and his website.
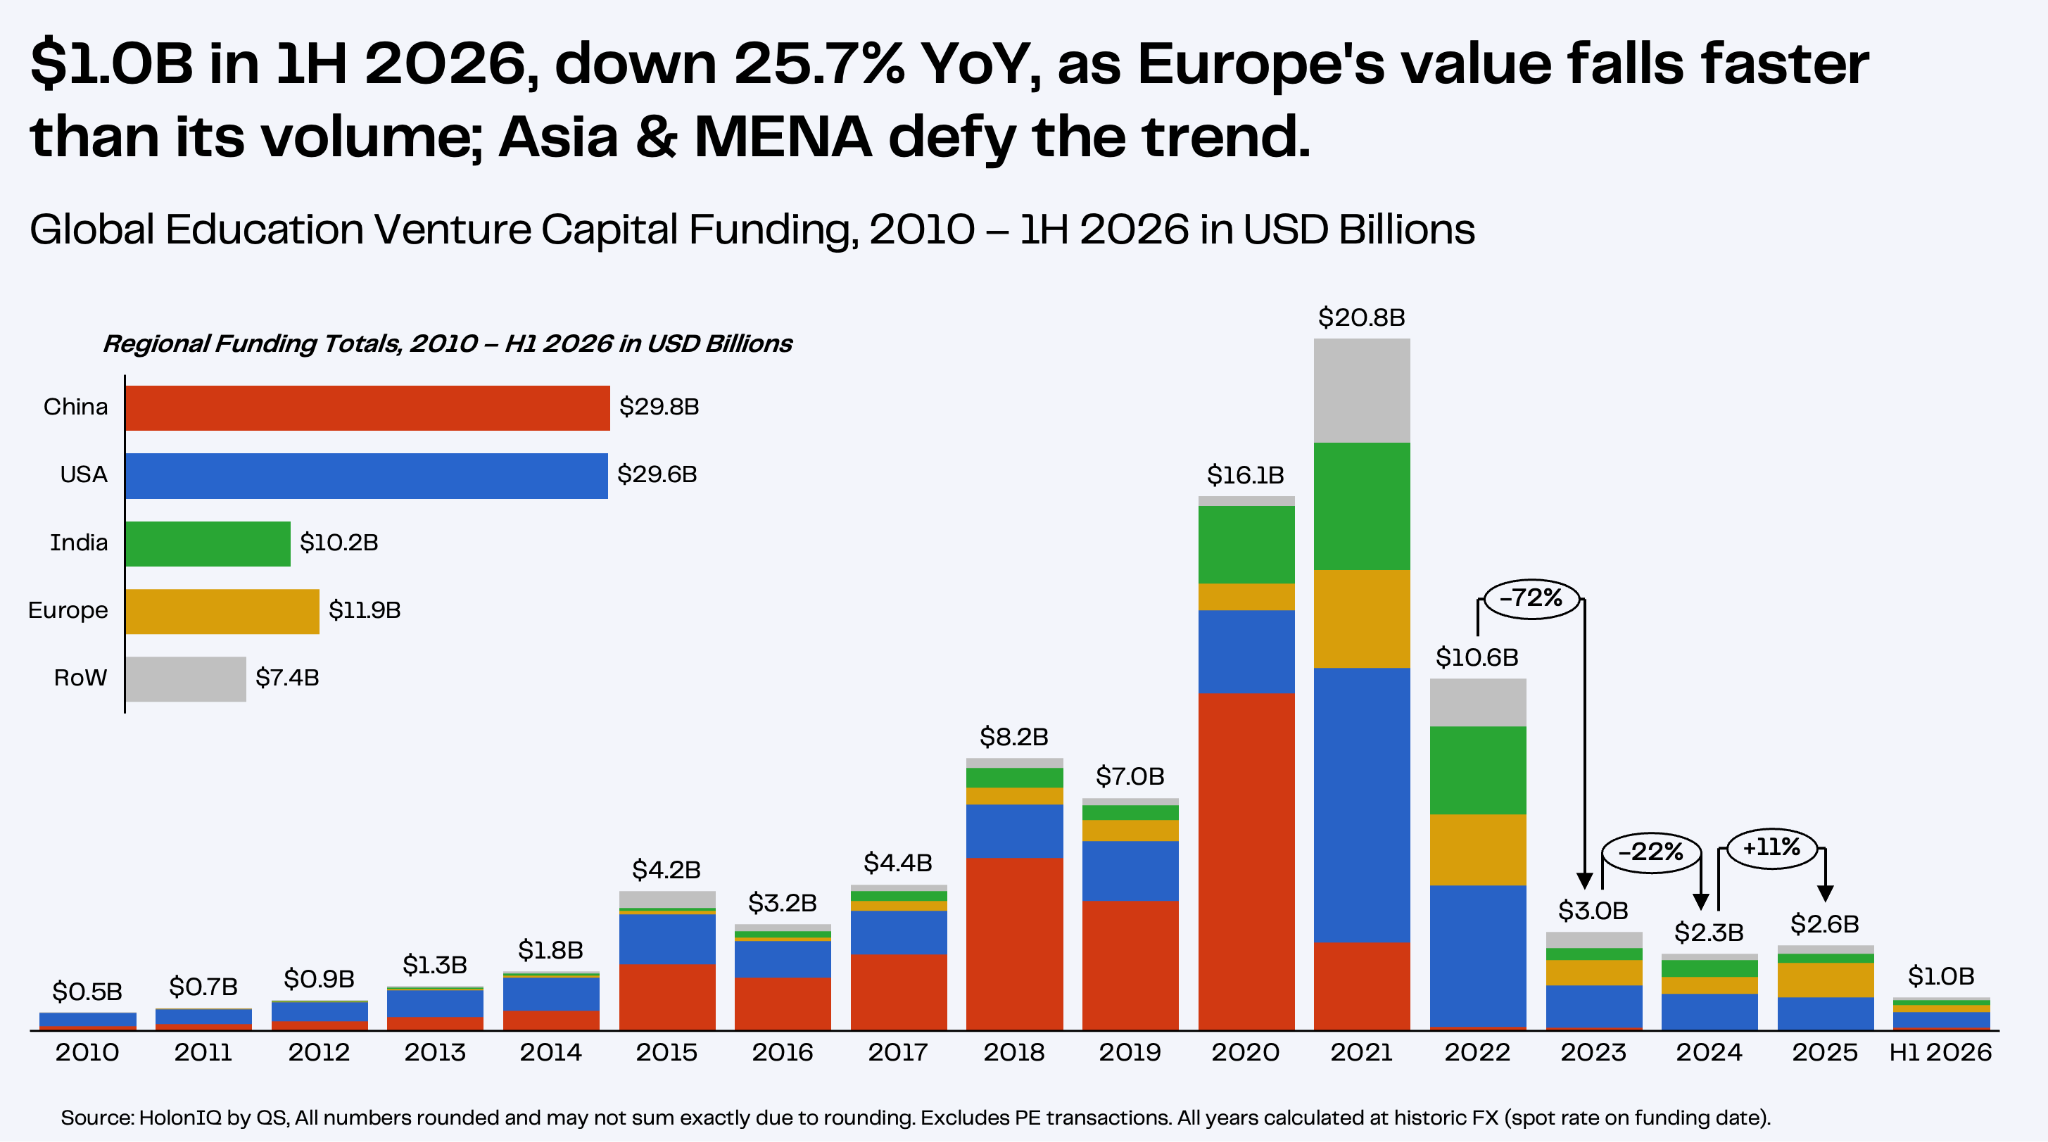
The post-COVID EdTech industry remains in trouble. Rather than being the driver of new industry growth, AI models have undercut revenue potential. The contrast between boundless AI-powered possibilities for learning and the near-term likelihood of scalable new ventures is stark. While it is unequivocally good that the lockdowns which triggered the 2020-21 investment surge are behind us, 2025 was down 68% from 2018’s pre-pandemic peak. Owl Ventures is looking at long-term opportunities in Africa and exploring industry intersections with HealthTech and FinTech. GSV Ventures, which has historically focused on the United States, is now shining a spotlight on Indian EdTech. Reach Capital has formally expanded its thesis and Brighteye Ventures now refers to their strategy as HumanOS.
There is more going on here than a pendulum swing from a world-shaking black swan event. The economic models and market narratives EdTech has relied on for 30 years have collapsed. We must rebuild both. If we can get the latter right, the former becomes way easier to solve.
Wider discussions about the impacts of social media, artificial intelligence, screen-based devices, and corporate responsibility across the broader tech industry have engulfed EdTech. Shrinking budgets have led schools to scrutinize student outcomes. A series of cybersecurity incidents has put IT teams on high alert. These are serious challenges and it’s understandable why pessimism presently pervades. EdTech, however, has always been a magnet for optimists devoted to learning and growth. Readiness to learn and grow is exactly what we need now to reestablish a shared understanding of who we are and what we do.
EdTech’s Identity Crisis
Questions of identity may seem abstract or irrelevant, but we can’t sell what we can’t name and explain. That’s as true of our industry as it is of all our products and services. In the days when textbooks and worksheets ruled the school, “education technology” was understood in contrast to “educational publishing.” EdTech represented solutions delivered via silicon and software rather than paper and ink. As that distinction is no longer meaningful, even pillars of the community now wonder if the name “EdTech” fits us anymore.
EdTech Insiders’ own Ben Kornell has repeatedly contemplated the matter on the Edtech Insiders’ podcast, reflecting on how he and Alex Sarlin have debated calling the show “Education Insiders” or “Learning Insiders”. The International Society for Technology in Education (ISTE) just renamed itself the International Society for Transforming Education. Computer-Using Educators (CUE) is now the California Association for Leading Innovation in Education (CALIE). The common thread in these approaches to the blurring of publishing and technology is that they erase technology from the conversation. While I understand the thinking, that approach comes at a cost. When we try to maintain relevance by invoking abstractions like “transformation” and “innovation,” we instead erode it by diffusing the value proposition of all industry participants.
There is a better way forward. By sharpening definitions and drawing clearer boundaries, we can focus our resource investments and set the stage for new entrepreneurial activity..
An Original Approach to Evaluating EdTech Opportunities
Formal definitions of EdTech already exist and so do excellent resources that categorize, organize, and track our output. The breadth of the institutional market is cataloged in detail by HolonIQ’s Global Education Market Taxonomy. Whiteboard Advisors and Phil Hill and Associates are standouts for analysis of market trends. The landscape of generative AI tools for K-12 was thoroughly mapped by EdTech Insiders. While each excels within its scope, it is difficult to assemble them into a larger whole. Fractures and gaps are evident.
In considering the existing definitions of EdTech, one thing stands out: they all have a very detached tone. A key element that has anchored me to the industry is a desire to have a positive impact on people’s lives. Any definition that I embrace has to incorporate a sense of mission and purpose. After some reflection, I came to a definition that I personally find meaningful:
EdTech is a set of tools and systems that expand access to effective instruction so that every learner can acquire a life-changing education.
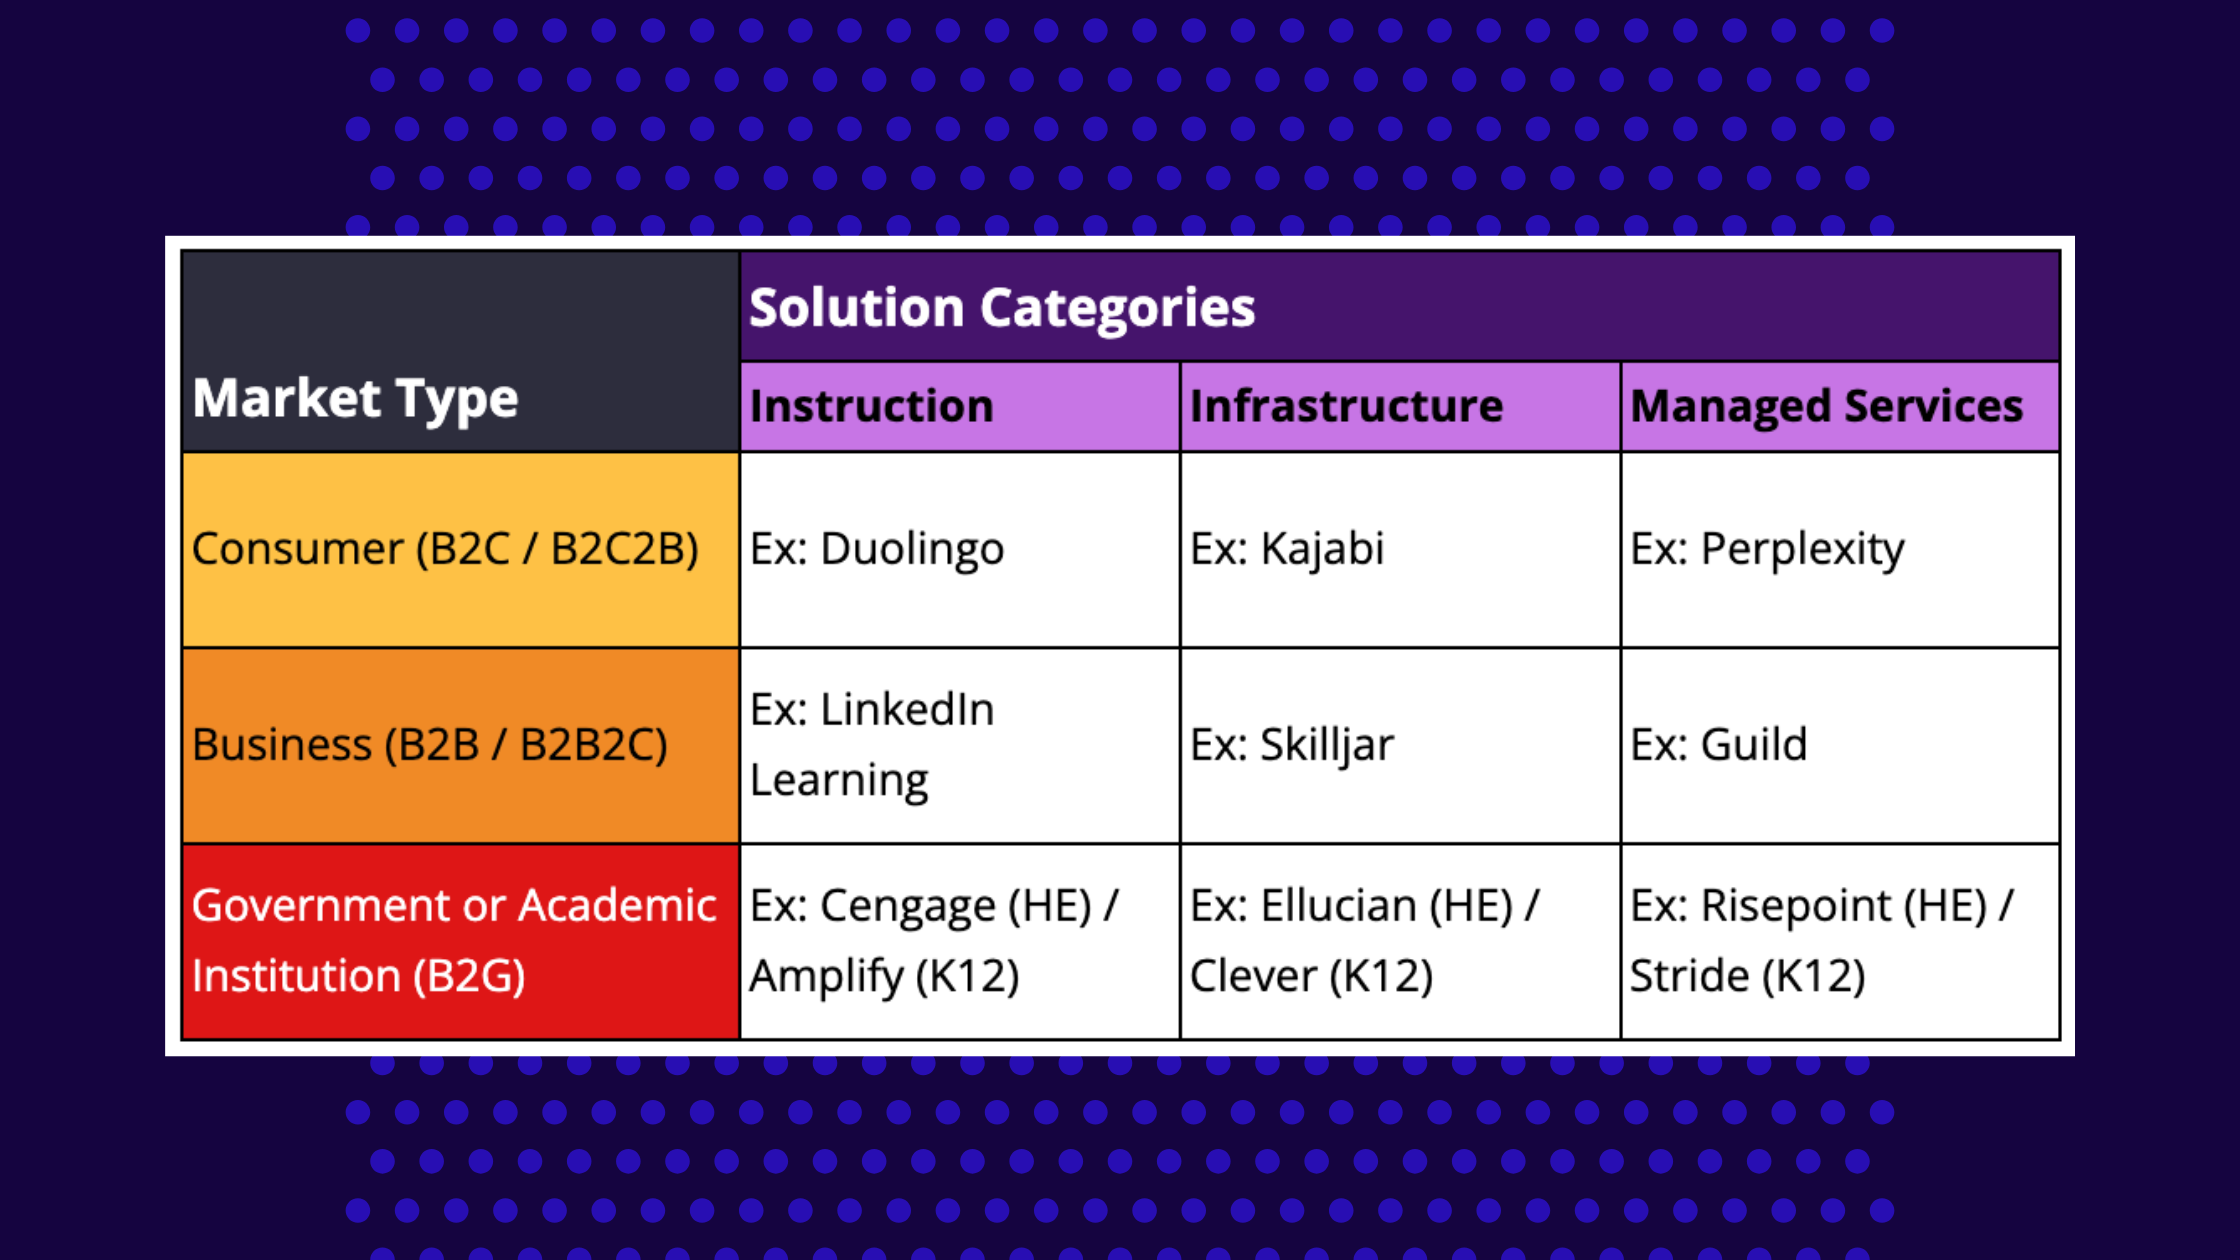
In systemically constructing a framework that encompasses the whole industry, that definition became the foundation. The framework which ultimately emerged is this 3x3 grid.
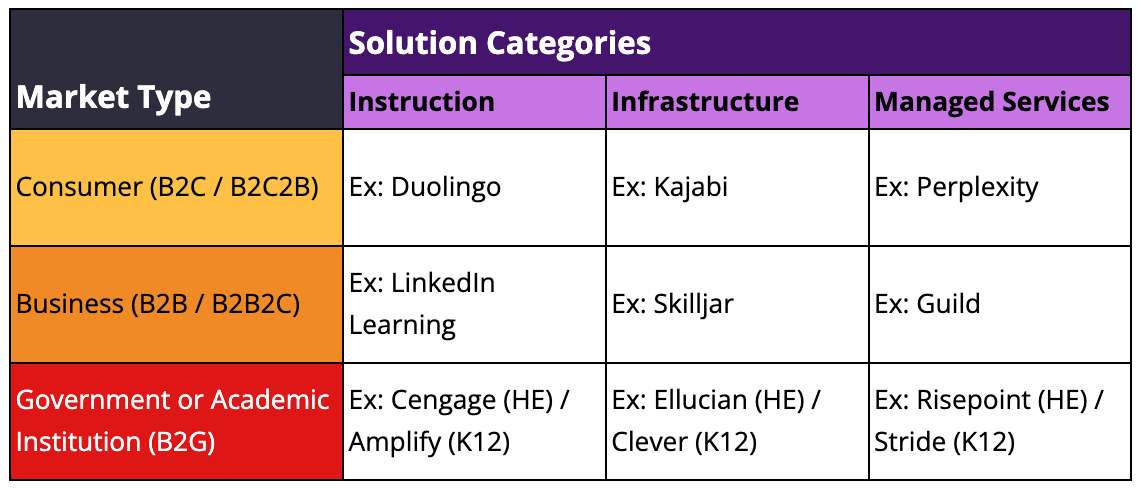
Intersections of market type and solution category create nine unique areas. As a starting point for understanding, I’ve provided examples in each area. When we think about companies that offer a range of solutions, some like Coursera do business in multiple areas. Others like LEGO have their core in a different industry entirely but work within EdTech at one or more junctions. Google arguably has solutions in all nine areas.
The basic structure is simple yet specific. When we unpack the dimensions, the framework enables much deeper exploration of business fundamentals without sacrificing cohesion.
The Solution Categories
Learn-to-read software that parents choose to download to a personal device for their four year old is EdTech. A student information system (SIS) used by a university with thousands of students is also EdTech. How can those two things be obviously different and yet the same? My interest in resolving that is what set this whole exercise in motion. I wanted to compare financial performance and couldn’t do that without categories. (I found that typical IRR is < 10% for Instruction and 15-20% for Infrastructure, although that comes with a lot of nuance.) Managed Services became its own category after a conversation about online program managers (OPMs) with Workshop Ventures’ Mike Berlin.
Assessment, a big topic in its own right, merits special mention as different assessment solutions belong in different categories. A question bank would be an instruction solution while lockdown software for high stakes exams is infrastructure. A standardized testing provider like ETS could be considered a managed service.

The Market Types
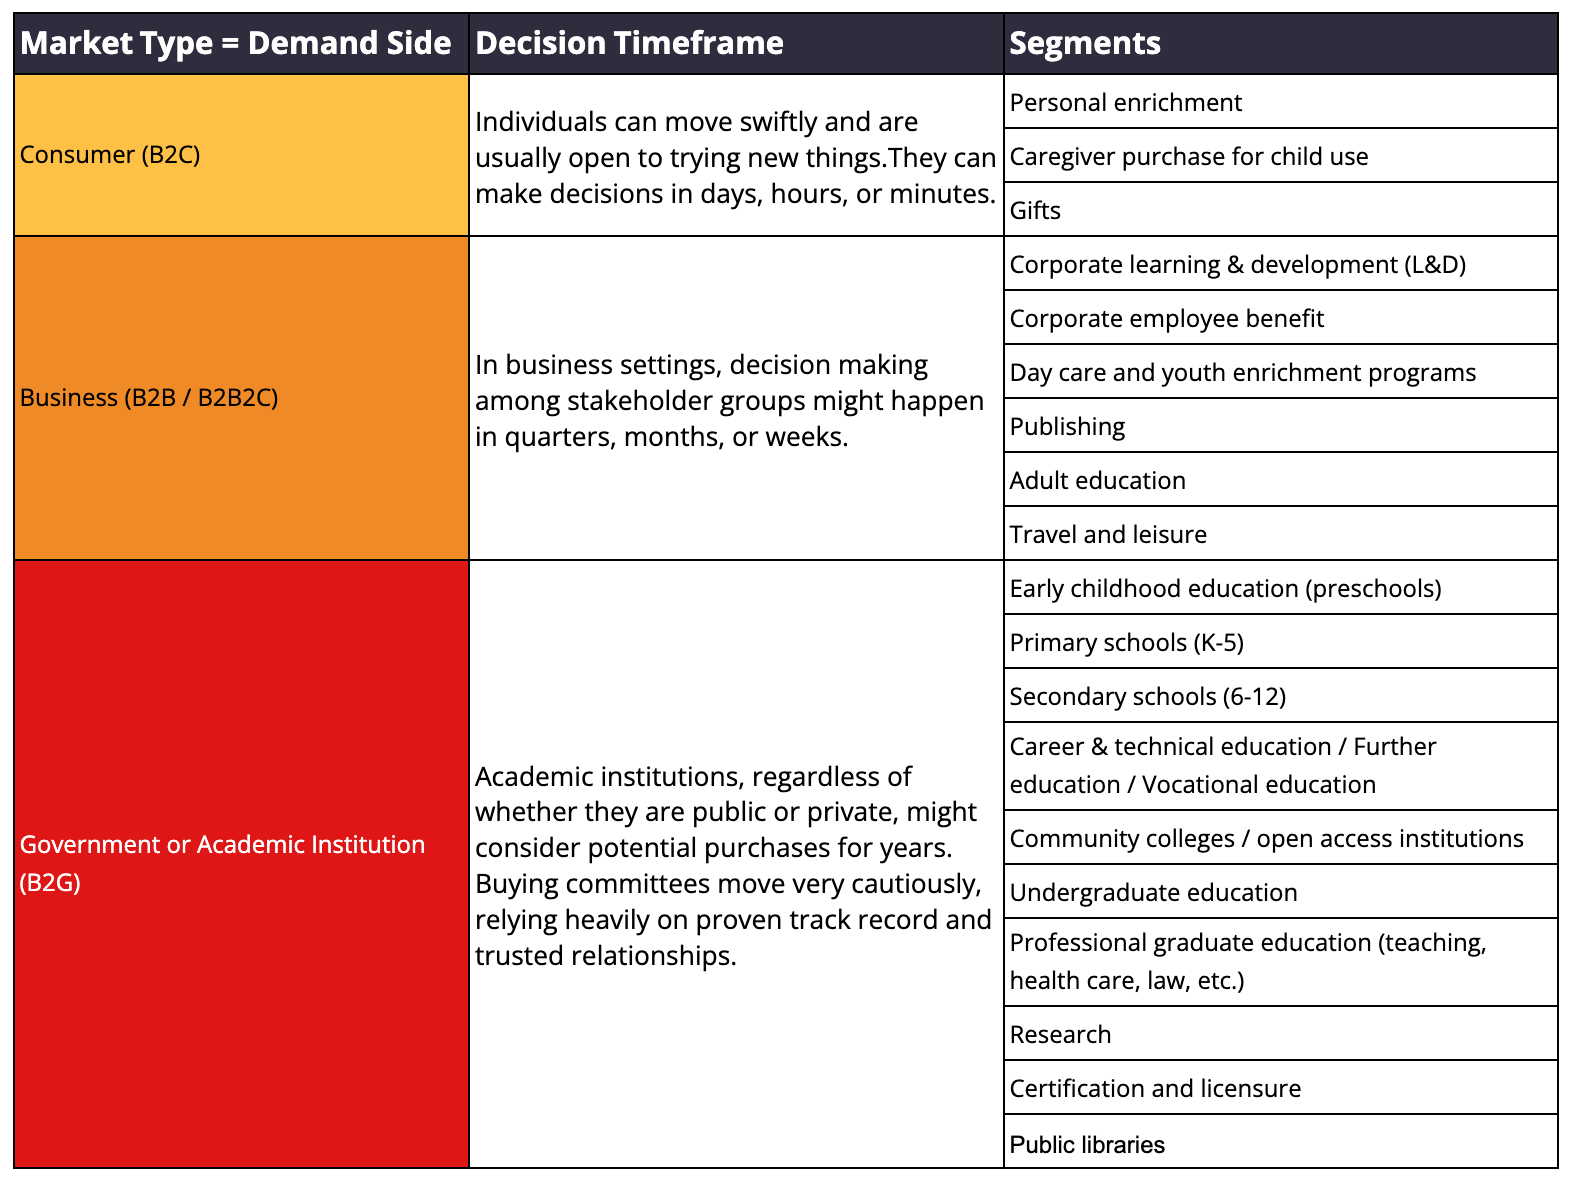
If we’re strictly applying textbook principles, it could be argued that making B2C / B2B / B2G a top-level split puts too much focus on the transaction when the priority should be the customer and their job to be done. The choice, however, wasn’t motivated by the number three’s aesthetic appeal. It’s born of an issue that I frequently encounter in my own practice.
I have spoken with many founders over the years who want to take the product they built around a consumer paradigm and apply corporate enterprise go-to-market motions — most commonly product-led growth (PLG) — in pursuit of large institutional deals in K-12 or Higher Ed. The problem is that what works in one setting doesn’t automatically translate into the others. The buying cycles and processes are completely different. When you look past the transaction, B2C / B2B / B2G is the crispest way I’ve found to characterize internal relationships and organizational context in a way that relates segments.
A Restarting Point
After 25 years in the industry, what I like most about this is the fresh questions I suddenly find myself asking. I never felt like I could fit all the pieces of the EdTech puzzle together and now I can. As an example using only reasoning from definitions, we can analyze the threat of new entrants in each of the nine areas.
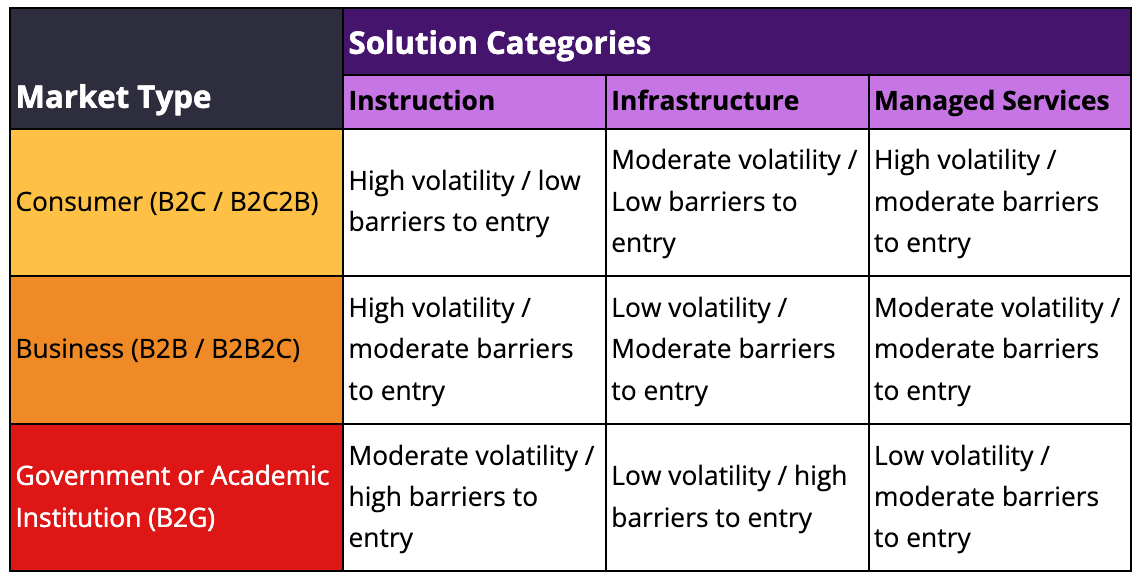
We now have an organized way for EdTech teams to discuss the potential risks and rewards of different market moves — and this is only the beginning. As mentioned, I’ve been collecting publicly available business data. I’m going to see what cross-area comparisons are possible and use that as a basis for potential case studies and white papers. Since my goal in sharing is to help us all find new ways forward as an industry, my hope is that the 3x3 framework sparks new questions for you too.
In the meantime, I’d appreciate your feedback in the comments section. How does this approach give you some new insight into EdTech? How does your novel product break the model? As fellow members of the EdTech Insiders Plus WhatsApp group will attest, I value rich conversations.
Thanks for reading! Support our work by becoming a paid subscriber, or email info@edtechinsiders.org to learn more about partnerships and sponsorships.
Upcoming Events

Bay Area Edtech Happy Hour
Thursday, August 20
5:00-6:30 PM PT
The GreyhoundSF
Join Edtech Insiders to celebrate back-to-school outside at The GreyhoundSF beer garden! Join us for drinks, discussion, and time to catch up with edtech community.

What Is the Future of Higher Education in America?
Friday, August 28
9:00-10:00 AM PT / Noon-1:00 PM ET
Webinar on Zoom
AI is reshaping learning, employers are rethinking credentials, and universities are facing unprecedented change. Join us for a live conversation with an incredible panel of experts exploring how higher education must evolve to remain relevant, accessible, and valuable in the decade ahead.
Join us live or register to receive the recording the following Wednesday.
Most Interesting Thing In Edtech
Hey Insiders! We are excited to be launching a new segment on our Substack that we’re calling “Most Interesting Thing In Edtech”. This will be a quick read covering a timely headline, why it matters, and what about it caught our eye.
Here’s a sample of what this will look like, and if you want to subscribe to this offering you can do so here, just toggle on the notifications for the publication “Most Interesting Thing in Edtech.” Reach out if you have any questions about this!
New Tutoring Benchmarks Continue to Reveal Gaps in AI Models for Teaching and Learning
There are two new interesting papers about education benchmarks for LLMs:
EduClaw-Bench evaluates AI-agent configurations over a 30-day learning horizon using simulated learners based on real knowledge-tracing data. Their study revealed that almost none of the model/agent combinations they studied (including GPT5.5 and Alibaba’s Qwen models) maintained strong tutoring performance over time; sustained tutoring demands ongoing capabilities like remembering learner progress, spacing practice, and maintaining strategy, suggesting the need for learner modeling, orchestration, and pedagogical memory. (arXiv)
The ELBench research benchmark evaluated nine models (seven general-purpose frontier systems and two education-specialized models) across general capability, safety/trustworthiness, basic education, and higher-order educational development. Specialized Models Underperformed: The two education-specialized models studied failed to lead in either of the education-specific modules. (arXiv)
Why It Matters
Edtech still lacks solid, universally accepted benchmarks to define what actually makes an AI product or tutor “good” at teaching and learning… but it’s not for lack of trying.
Learning Commons has been publicly building a suite of ‘evaluators’ of Edtech tool outputs
Google has developed a thoughtful internal rubric to evaluate the pedagogical value of its LLM outputs
Digital Promise recently announced the recipients of the first grants from its K-12 Infrastructure program which include funding for benchmarks
…and last, but not at all least, research teams around the world have been suggesting lots of clever ways to benchmark the outputs of LLM models and their agents/harnesses/product delivery systems.
Our Take
As always, the gap between research and practice is vast and most Edtech companies are not even attempting to benchmark their own products against any of these research-lab-released benchmarks.
That said, maybe they should… at least one lead VC in the field is paying close attention. Here’s a quote from Jennifer Carolan of Reach Capital on Alison Dulin Salisbury’s excellent Humanist Substack:
ALLISON: What have you changed your mind about in the past year?
JENNIFER: I changed my mind about how useful AI tutors are becoming. The underlying technology is improving more quickly than I had ever imagined which is rapidly improving the quality of the AI tutors. Combined with the changes happening in society writ large, these AI tutors may become one of the primary drivers of change of our current formal education system.
I teach a class at Stanford with Steve Blank called Lean Launchpad, and we’ve been so blown away by how quickly students built working prototypes this year—like, Week Two. We’ve had a couple of education teams in this cohort, and it’s been fascinating to see how fast they created compelling AI tutors. In just a few weeks, one team made the leaderboard for Scale AI’s “TutorBench” evaluation—a benchmark for assessing AI tutor quality—so we’ve watched the speed at which these tutors improve in almost real time. Tutors are meeting a pivotal moment, as higher ed is getting pushed hard on ROI and K-12 is under tremendous pressure.

How Boddle Turned Classroom Math into a Game Kids Choose to Play
Edna Martinson is the Co-Founder and COO of Boddle Learning, a gamified K–6 learning platform used by millions of students to build confidence in math, literacy, and science. She is passionate about combining great game design with research-backed learning experiences that teachers and students love.
5 Things You’ll Learn in This Episode
Why Boddle was built to compete with video games.
How gamification drives learning and confidence.
What teachers want from classroom technology.
How AI is shaping Boddle’s future.
The next evolution of personalized learning.
Thanks for reading! Support our work by becoming a paid subscriber, or email info@edtechinsiders.org to learn more about partnerships and sponsorships.
I completely agree with your 3x3 framework on how to segregate the EdTech industry. This makes good sense. Nice job!
A great read, which is not at all surprising when taking in insights from Ian! I spend a lot of time segmenting the EdTech world myself, mostly to help me understand who all the players are and where they fall in this complex ecosystem. I spent last month updating the categories and are currently sitting at the following: 1. Core Curriculum, Supplemental, CTE/STEM 2. Big Tech 3. Assessment, Data, and Accountability 4. K12 Virtual and Charter 5. Student Support, Tutoring, Intervention. 5. Learning Platforms, LMS, & Course Delivery. 6. Educator PD/PL. 7. Authoring Content Creation, Digital Resources. 8. AI in Education, Workflow Automation, 9. Higher Ed. 10. Workforce Upskilling. 11. Consultants and Contractors. 12. ECE. 13. School Operations, SIS, Finance, & Admin systems